
Tax dispute resolution
How to Use a Tax Accountant When Challenging a Tax Assessment
Addressing a Tax Assessment with Evidence and Reasoning
The tax office has issued a decision, but you disagree with it.
Is the disagreement about the facts, the interpretation of law, or the application of law to the facts? We begin by helping clarify what should be challenged.
We accept individual engagements from clients without an ongoing advisory contract as well as existing clients. Our principal and tax accountant, Kenji Yanagisawa, examines documents, evidence, and the basis of taxation and develops a strategy with reinvestigation requests, National Tax Tribunal review, and possible litigation in mind.
If You Have Already Received a Tax Decision
When contacting us, please tell us the nature of the decision and the date you received notice. Requests for reinvestigation and requests for review generally must be filed within three months from the day after receipt of the notice. Please also state if the deadline is approaching.
An inquiry alone does not complete an appeal procedure or extend any deadline. We will review the circumstances and advise you, including whether we can accept the engagement.
How do tax disputes differ from tax litigation?
Tax disputes broadly encompass legal disputes about taxation. They are resolved primarily through two channels: administrative and judicial. Tax litigation in court is one part of this broader field.
The Full Range of Disputes Concerning Taxes
Administrative proceedings: appeals
These include requests for reinvestigation by a tax office director or similar authority and requests for review by the National Tax Tribunal. Certified tax accountants may act as representatives in these procedures; our office prepares submissions, organizes evidence, and presents arguments and explanations.
Judicial proceedings: tax litigation
These are court proceedings seeking cancellation of an assessment or other relief. Where an external professional represents you in litigation, a lawyer generally handles that role. We introduce partner lawyers experienced in tax litigation and collaborate on the tax aspects.
A tax accountant alone cannot act as litigation counsel in court. We have therefore built relationships with several lawyers experienced in tax litigation. We connect the facts, evidence, and tax issues developed at the administrative stage to arguments before the courts.
Do Not Stop at “Because the Tax Office Says So”
Tax judgments are grounded in legal reasoning: identify the statutory requirements, establish the facts through evidence, and apply the law to those facts to reach a conclusion.
A tax dispute calls for more than repeating dissatisfaction:identify errors in fact-finding, legal interpretation, or application of the law, supported by evidence. We review assessment notices, communications during the audit, tax returns, agreements, books, and other materials to develop the issues and arguments.
We assess not only the basis of your arguments but also contrary evidence and difficult points. Rather than making dispute itself the objective, we develop a response with the taxpayer by weighing expected benefits against cost and time.
From a Tax Audit to an Administrative Appeal or Tax Litigation
If the Matter Is Still at the Audit Stage
We first present the facts and supporting grounds during the audit. We consider whether the issue can be resolved before a formal decision and carefully assess whether to file an amended return.
Tax Audit Support →After an Assessment Has Been Issued
We consider an administrative appeal seeking cancellation or amendment of the assessment. An amended return is filed by the taxpayer and is not itself subject to administrative appeal.
If a return overstates tax, a request for correction may be possible if the requirements and deadline are met.
- Request for Reinvestigation or Request for Review
In principle, you may choose between requesting reinvestigation by the tax office director or similar authority and requesting review by the National Tax Tribunal. You may request review directly without first seeking reinvestigation. - Review and decision by the National Tax Tribunal
You submit arguments and evidence for review of the issues. If you first request reinvestigation and remain dissatisfied with the decision, a request for review must generally be filed within one month from the day after service of the certified copy of the decision. - Tax litigation in court
If you remain dissatisfied with the assessment after the tribunal's decision, proceedings must generally be brought in a district court within 6 months from the day after you learn of the decision. In certain circumstances, exceptions allow filing before the tribunal decides.
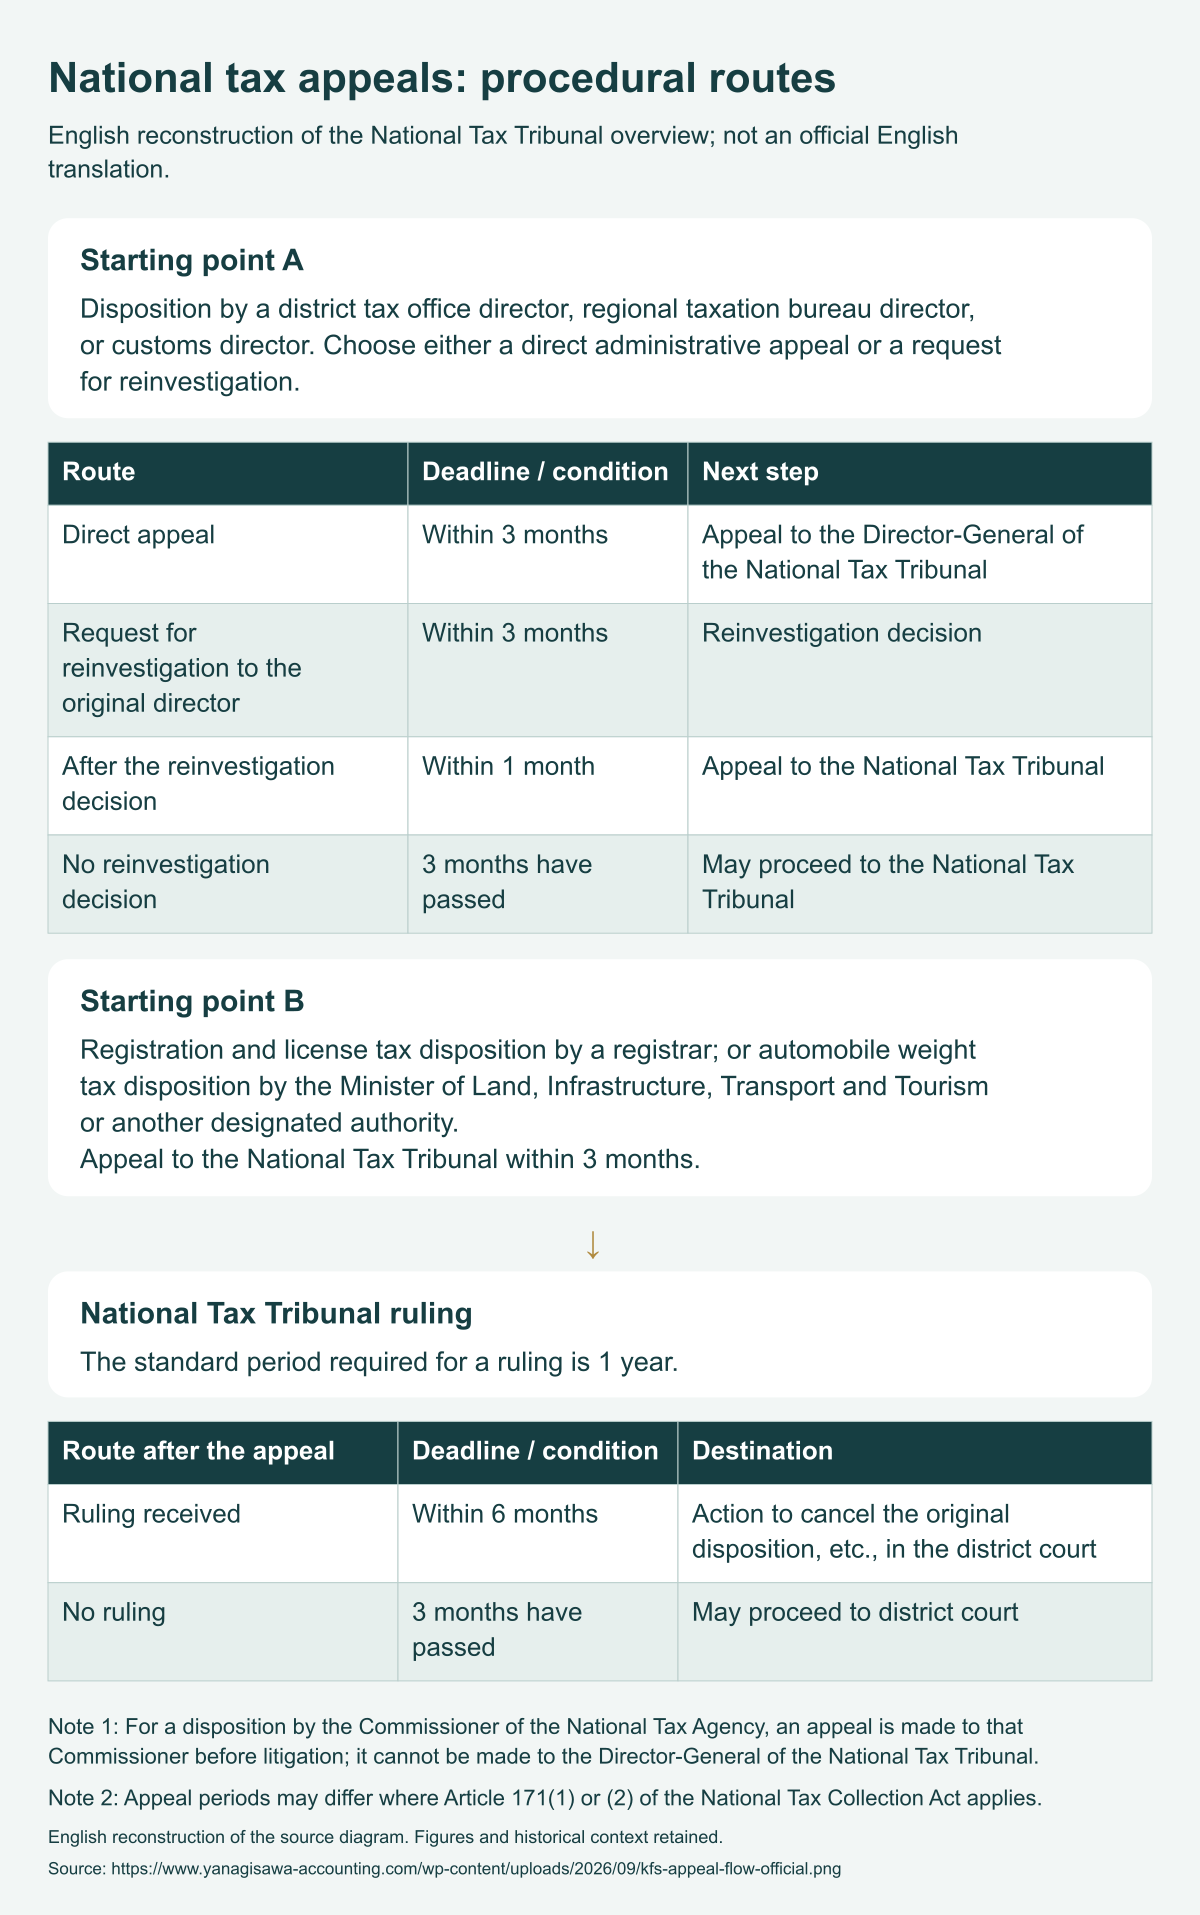
Litigation may proceed from a district court to a high court and then to the Supreme Court. Appeals have requirements and deadlines, however, and not every case reaches the Supreme Court.
Details of the procedure:National Tax Tribunal: Appeal Procedures/National Tax Agency: “When an Administrative Appeal Is and Is Not Available”
How We Support You
- Reviewing the assessment, facts, evidence, and legal issues
- Preparation of requests for reinvestigation, requests for review, rebuttals, and other submissions
- Tax representation after preparing the required power-of-attorney and related documents
- Oral statements and responses to questions, inspections, and other review procedures
- Working with lawyers experienced in tax litigation, including tax analysis and organization of materials
A lawyer acts as litigation counsel in court. As tax accountants, we support the case by organizing tax issues and evidence. We clarify roles and the scope of work in advance according to the engagement.
Issues We Have Handled
In administrative appeals and requests for review, including objections under the former system, we have handled cases such as the following.
- Excessive director remuneration and retirement benefits
- Withholding obligations on payments to nonresidents
- Resident or nonresident status
- Secondary tax liability
Challenging the government on tax is not easy
According to FY2025 statistics published by the National Tax Agency and other bodies, the proportion of requests for review upheld was7.2%, while the government's loss rate in tax litigation was4.0%. Both figures include partial successes or partial defeats, respectively.
However, these annual statistics use all disposed or concluded cases, including withdrawals and dismissals, as the denominator. They do not indicate the probability of success in an individual case or the ability of a particular professional.
Even so, the importance of thoroughly examining facts and law and working with specialists suited to the issues remains unchanged. In cooperation with partner lawyers experienced in tax litigation, we have supported taxpayers in cases such as the following.
Source:Overview of Requests for Review in FY2025/Overview of Litigation in FY2025
Our involvement in tax litigation
- Takefuji gift tax case: Supreme Court judgment in favor of the taxpayer (2011) →
After the High Court judgment, we supported the taxpayer on tax matters by advising on non-resident status and domicile and providing academic papers. - Nonresident status following relocation to Singapore: Partial taxpayer victory in Tokyo District Court, now final (2023) →
Lawyers acted as litigation counsel, while our office assisted as a tax accounting adviser.
Each example is based on its own facts and applicable laws and does not guarantee a similar outcome.
Indicative fees
| Initial consultation on your specific circumstances | JPY 55,000 per hour Where consumption tax applies, it is included in the displayed price. Where export exemption applies, the full displayed amount is the consultation fee. Your total payment remains the same in either case. |
|---|---|
| Preparing a request for reinvestigation | From JPY 1,000,000 (JPY 1,100,000 including tax) |
| Preparation of the request for examination | From JPY 1,000,000 (JPY 1,100,000 including tax) |
| Preparation of the written rebuttal | From JPY 1,000,000 (JPY 1,100,000 including tax) |
| Oral statement / Response to questioning inspection Existing Advisory Clients | JPY 30,000 per half day (JPY 33,000 including tax) |
| Oral statement / Response to questioning inspection One-Off Engagements | From JPY 50,000 per hour (JPY 55,000 including tax) |
| Indicative Success Fee | From 10% of the economic benefit (reduction in additional tax assessed), excluding consumption tax |
We provide a quotation based on document volume, issue complexity, and the work required. Before engagement, we explain the scope of drafting, research, analysis, and representation, and the use or combination of fixed fees, hourly charges, and success fees. The basis for calculating success fees is also specified in the individual agreement. Litigation counsel's fees are separate.
Choose How You Would Like to Consult Us.
Consult Directly with Kenji Yanagisawa, Principal and Certified Tax Accountant
For a direct 60-minute consultation with our principal, tax accountant Kenji Yanagisawa, without a preliminary email inquiry, book here. The fee is JPY 55,000 for either an online or in-person consultation.
Where consumption tax applies, it is included in the displayed price. Where export exemption applies, the full displayed amount is the consultation fee. Your total payment remains the same in either case.
You will proceed to the card payment screen. After your application, we will arrange the consultation date, time, and format.
Start with an Email Inquiry
Email inquiries are free. Tell us about the issue you are facing or what you would like to discuss. We will review your inquiry and recommend a paid consultation if you need specific tax judgments or advice.
There is no charge for submitting an inquiry. Please also use this form if you prefer to pay by bank transfer.
Preparation of appeal documents and representation require a separate engagement. Please have documents showing the notification date of the assessment and relevant deadlines ready.